

myEquifax

- 988.00 Reviews
- 4.6
- Downloads
- 500,000+
Our take on myEquifax from Appgk
Managing credit is one of those jobs that usually begins with a small worry: a card application is coming up, a loan decision is pending, or an unfamiliar account has appeared in your records. I found that myEquifax is built for that starting point. It is a free finance app from Equifax Incorporated that puts the Equifax side of your credit journey into a mobile format, rather than making you begin with a browser search or a pile of paperwork.
That sounds simple, but the useful part is the workflow. You open the app because you want to understand your current position, look for something that needs attention, and decide what to do next. It is not a budgeting app, a general banking app, or a replacement for every credit service. Its value is narrower and more practical: it gives you a direct place to engage with Equifax information and credit-related tasks.
I would recommend approaching it as a monitoring and decision-support tool, not as a magic button that repairs credit. That distinction matters. The app can help you notice issues and organize your next move, but improving a credit profile still depends on what happens outside the app: checking statements, contacting the right company, paying obligations on time, and allowing corrections or updates to work through the relevant systems.
From a vague credit worry to a clear first check
The best use case begins with a specific question. Perhaps you are preparing to apply for credit and want to review your position first. Perhaps you received a notice that does not match your memory. Or perhaps you simply want a regular habit for keeping an eye on your credit information. In each case, the first useful action is the same: open myEquifax and treat the session as an investigation rather than a quick glance.
Best Parts of myEquifax
Things to Keep in Mind About myEquifax
I like that framing because credit information is easy to misunderstand when it is viewed in isolation. A number or account entry may look alarming until you consider its date, status, or relationship to a recent application. The app is most helpful when I slow down, read what is shown, and write down the question that remains unanswered. That prevents the common mistake of reacting to one screen without understanding the wider context.
The app is rated at an average of 4.6 from around eleven thousand ratings, and it has passed half a million installs. Those figures suggest that it has found a substantial audience, but they should not replace your own test of whether its presentation suits you. Credit tools are personal: a clear screen for one person can feel too limited or too cautious for another.
News and Features Related to myEquifax

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Because it is rated for Everyone, the app is approachable for a broad audience. Still, “easy to open” is not the same as “easy to interpret.” I would not hand the phone to a teenager or a first-time credit user and assume every term will be obvious. The strongest experience comes when the user is willing to pause, compare the information with their own records, and avoid making a financial decision based on a single unexplained detail.
What I would prepare before opening it
A little preparation makes the first session much less frustrating. I would have a recent statement or account list nearby, along with approximate dates for any recent applications, account openings, or changes. I would not expect the app to replace those documents. Instead, they give me something to compare against when I am checking whether the information shown matches my own history.
Don't want to read the full review?
I would also decide what outcome I want. “Check my credit” is too broad to guide a useful review. A better goal is “confirm that the account I closed is reflected correctly,” “understand what I should review before applying,” or “identify whether an unfamiliar entry needs follow-up.” This turns the app from a passive dashboard into the first step of a concrete workflow.
There is a subtle advantage to this approach: it separates observation from action. First I record what appears. Then I decide whether the next step belongs with Equifax, a lender, an issuer, or myself. That separation reduces the chance of contacting the wrong organization or assuming that every discrepancy has the same cause.
Screenshots
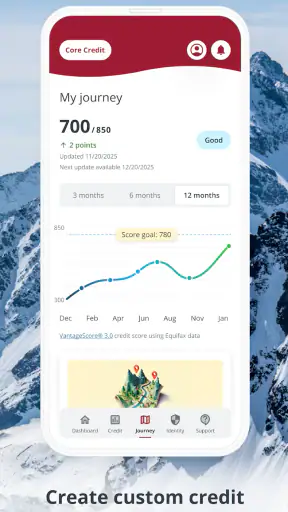
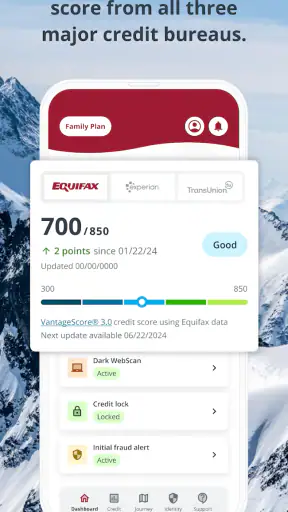
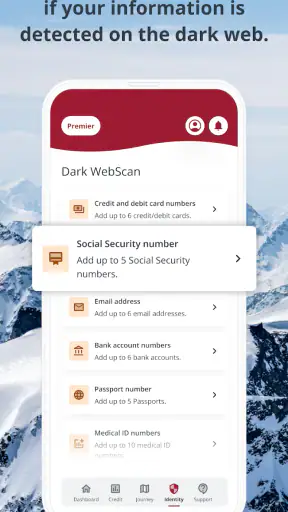
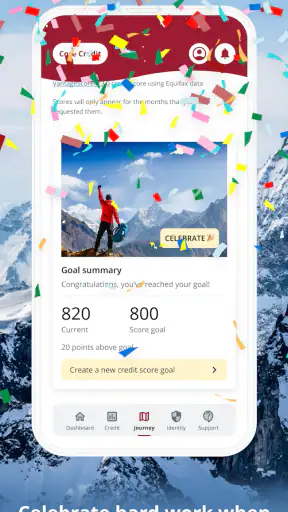
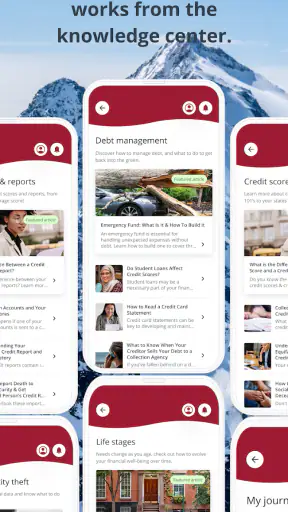
How the complete workflow feels in practice
Step one: enter with a question, not a panic
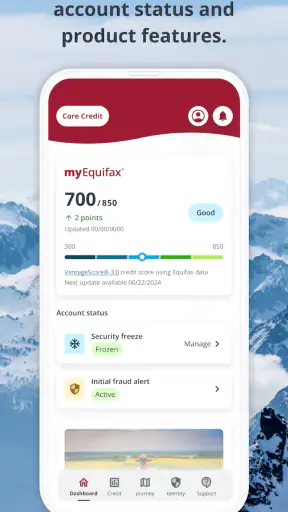
When I start, I look for the clearest overview available and resist the temptation to jump immediately to the most worrying item. The opening view should answer a basic question: what part of my credit journey am I reviewing today? If I am checking before an application, I focus on the overall picture. If I am investigating a possible error, I move toward the account or event connected to my concern.
This is where myEquifax differs from a general personal-finance app. A budgeting tool may show spending, balances, and cash flow across accounts, but it usually does not serve as my direct Equifax workspace. Conversely, a lender’s app may show the relationship I have with that lender while leaving the wider credit picture elsewhere. I see this app as the bridge to Equifax-specific information, not as a universal financial command center.
The practical tip is to take a screenshot or written note only after I understand what the screen represents. A saved image without context can become confusing later, especially if I am comparing it with a statement or communicating with support. I record the name of the item, its apparent status, and why it matters to me. That small habit creates a useful trail for the next handoff.
Step two: inspect the detail behind the headline
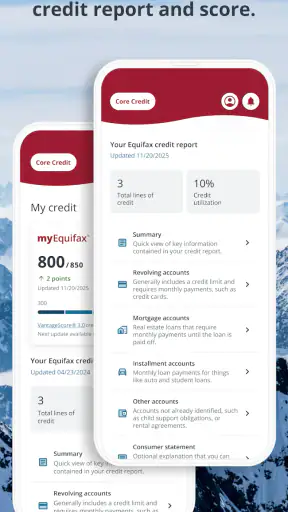
A headline can tell me that something deserves attention, but the detail is where the decision begins. I look for the identifiers and timing that help me recognize an account or event. If the entry is familiar, I compare it with my own records. If it is unfamiliar, I avoid guessing whether it is fraud, a reporting delay, a name variation, or an account connected to an organization I recognize under a different label.
This is one of the most important trade-offs in a credit app: speed versus interpretation. A quick summary is useful for orientation, while detailed review takes longer but gives me a better basis for action. I would rather spend a few extra minutes confirming what I am looking at than immediately dispute something that turns out to be legitimate.
Another useful workflow is to review changes in context. A recent application, account closure, payment update, or transfer may not appear exactly when I expect it. That does not automatically make the information wrong. The app can help me see what is currently associated with my Equifax file, but I still need to compare it with the dates and records held by the company involved.
Step three: decide who owns the next action
This is the handoff that many users overlook. If I find an issue, the next step depends on what kind of issue it is. A question about how a lender reported an account may need to go to that lender. A concern about information in the Equifax file may require an Equifax-related route. A suspected security problem may involve several organizations and a more urgent response.
myEquifax is useful here because it gives me a place to begin the review, but I should not expect one app to settle every disagreement between a consumer and a creditor. The app is not the same thing as the institution that originated the account, and it cannot make a lender change a record simply because I noticed it. The realistic outcome is better organization: I can identify the issue, gather supporting details, and approach the correct party with a clearer explanation.
I also recommend keeping the language factual during this handoff. Instead of saying “my credit is broken,” I would describe the account, the date, the discrepancy, and the correction I am requesting. That makes the conversation easier for the receiving organization to understand. The app starts the process; the quality of the information I carry into the next conversation affects what happens afterward.
Step four: turn the review into a repeatable habit
One inspection is helpful, but a repeatable routine is more valuable. I would use the app when there is a genuine reason to review my credit and after meaningful financial changes, rather than constantly refreshing it for reassurance. Checking too often can encourage overreaction to normal movement or timing differences.
A simple routine is to choose a calm moment, review the overview, inspect anything unfamiliar, compare important entries with personal records, and note any follow-up. The note should include the action and the organization responsible for it. This is a more useful outcome than merely remembering that I opened the app.
For someone rebuilding credit, the app can serve as a checkpoint between longer-term habits. I can use it to stay aware while I focus on the actions that actually shape my situation, such as managing payments and avoiding unnecessary applications. For someone with stable finances, it may be most useful before a major application or when checking whether an old account is represented as expected.
A realistic everyday scenario
Imagine I am planning to apply for an auto loan. Before speaking with a lender, I open myEquifax and review the information connected with my credit profile. I notice an account I recognize, but its status does not match the paperwork I kept when I finished dealing with it. Rather than applying immediately, I note the account details and compare them with my statement.
At that point, the app has already produced a useful result even though it has not fixed anything. It has changed my next action from “submit an application and hope” to “clarify a possible reporting issue first.” I contact the organization associated with the account, explain the mismatch, and keep the response with my records. If the matter also requires attention from Equifax, I now have a more precise description to carry into that process.
This scenario shows the app’s strongest role: it can reduce surprises by encouraging a review before a consequential decision. It cannot promise that a lender will approve me, and it should not be treated as a prediction of the final terms I will receive. It helps me prepare; the lender still makes its own assessment.
Where the workflow is smooth and where it breaks
The handoff from app to real-world records
The biggest friction appears when the information in the app and the information in my own documents do not line up. That mismatch is precisely why I opened the app, but it also creates the most work. I have to determine whether the difference comes from timing, terminology, an update that has not appeared, or a genuine reporting problem.
This is not a flaw unique to myEquifax, but it is important when comparing it with alternatives. A bank app may feel more immediately familiar because it shows transactions and account details from a relationship I already manage there. A credit-monitoring service may offer a broader multi-source view, depending on its own coverage and design. myEquifax makes more sense when I specifically want to work with the Equifax side of the picture and prefer to begin with the source associated with that file.
The trade-off is concentration. I get a focused route into one credit bureau’s environment, not a complete replacement for checking other sources or contacting account providers. If I am preparing for a major financial decision, I would not assume that one app gives me every relevant perspective. It is better used as one carefully understood part of a wider review.
Account access and the cost of security
Financial apps have to be more deliberate about access than ordinary entertainment apps, and that can make the first session feel slower. Verification steps, identity checks, or account-recovery problems can interrupt the flow. I consider that friction preferable to a casual approach to sensitive credit information, but it still affects the experience when I am trying to deal with an urgent concern.
I would make sure I use the correct personal details and keep any account-recovery information current. I would also avoid treating a shared or borrowed device as a convenient shortcut. The app may be free, but free does not mean the information is low-stakes. The real cost of a careless session could be confusion, exposure, or a delayed response to a problem.
For users who dislike identity-heavy financial services, this may be the point where another option feels easier. That does not necessarily make the alternative better for credit accuracy or relevance. It simply means the user values a faster, lighter experience more than direct access to this particular credit workflow.
Version, device fit, and expectations
The current version is 1.11.0, and the app supports devices running Android 8.0 or later. That makes it a realistic option for people who keep an older Android phone, although device age can still affect comfort, speed, and how easily sensitive screens are read. I would update the app through the normal store process and avoid judging the entire service from one slow session on an aging device.
The release date is April 25, 2025, so I would approach it as a relatively recent mobile product rather than a tool with a long personal history on my phone. That does not tell me whether every future change will be good or bad, but it does reinforce the value of checking the current interface when returning after a long gap. A workflow that feels familiar today may be reorganized in a later update.
People on iOS should pay attention to the platform version available to them before planning around the app. I would not assume that an Android requirement automatically describes the iPhone experience. The important practical question is whether the app is available and comfortable on the device I intend to use, especially if I need access while handling a time-sensitive credit matter.
Who should use it, and who should skip it?
I think myEquifax is a good fit for someone who wants a direct, focused way to begin reviewing Equifax credit information from a phone. It is particularly useful for a person preparing for an application, checking an account after a major change, or creating a calmer habit around credit awareness. The free price also lowers the barrier to trying it without committing to a paid finance service.
I would be more cautious about recommending it to someone seeking a full household-finance dashboard. If the main goal is tracking spending, categorizing purchases, planning bills, or viewing balances across banks, a budgeting or banking app is likely the better center of daily activity. This app belongs beside those tools, not in place of them.
I would also tell a user with a suspected urgent identity problem not to rely on opening the app alone. The app can be part of the evidence-gathering process, but urgent concerns may require prompt contact with the relevant financial institutions and appropriate protective steps. Waiting for a convenient in-app review would be the wrong workflow in that situation.
My final take after following the whole path
myEquifax works best when I use it as the first checkpoint in a chain: concern, review, comparison, handoff, and follow-up. Its strength is focus. Rather than pretending to be every kind of finance tool, it gives users a mobile entry point for their Equifax credit journey. That makes it easier to begin with a real question and carry a more organized answer into the next conversation.
Its limitations are just as important. It does not remove the need to understand credit terms, compare information with personal records, or contact the organization responsible for an account. It is not a substitute for a lender’s decision, a bank’s transaction history, or disciplined financial habits. The workflow can also slow down when access, identity verification, or conflicting records enter the picture.
Still, I would keep it installed if Equifax is the credit source I want to monitor and I prefer handling the first review on my phone. The free app, broad Everyone rating, and focused purpose make it easy to try. My advice is to use it deliberately: open it before an important application, investigate details rather than headlines, document what you find, and treat the handoff to the right organization as part of the solution. Used that way, it becomes more than a quick credit glance; it becomes a practical starting point for making better-informed financial decisions.
myEquifax FAQ
What is myEquifax, and what can I use it for?
myEquifax is Equifax’s mobile and online service for accessing personal credit information and related identity-protection tools. Depending on your country, plan, and account eligibility, you may be able to review your Equifax credit report, monitor changes, receive alerts, manage identity-protection features, and view educational information about credit. Available functions can vary by region and subscription, so check the official listing before downloading.
Is myEquifax free to download and use?
The myEquifax app is generally free to download, but not every feature is necessarily free. Basic account access or a credit report offer may be available without payment, while ongoing monitoring, identity-restoration assistance, additional reports, or other premium services may require a subscription. Before entering payment details, carefully review the current pricing, renewal terms, trial conditions, and cancellation policy shown in the app or on Equifax’s official website.
What information do I need to create a myEquifax account?
To register, myEquifax may request identifying and security information such as your legal name, address, date of birth, email address, phone number, and government-issued identification details or other information used to verify your identity. You may also need to answer knowledge-based questions. Use only the official app or Equifax website, avoid sharing login codes, and make sure the account details match your credit-file information.
Can myEquifax help me detect identity theft or errors on my credit report?
myEquifax can help you review your Equifax credit information and, where available, receive alerts about certain changes or activity. These tools may make unusual events easier to notice, but they cannot prevent every type of fraud and may not cover all credit bureaus, lenders, or accounts. If you find inaccurate information or suspect identity theft, follow Equifax’s dispute and fraud-reporting procedures and contact affected companies promptly.
Is myEquifax safe, and what should I do if I cannot log in?
myEquifax uses account authentication and security measures intended to protect sensitive personal and financial information, but users should still enable available security options, create a unique password, keep the app updated, and avoid logging in through suspicious links or public devices. If access fails, use the official password-reset or account-recovery process. Do not create duplicate accounts immediately, and contact Equifax support if verification or recovery remains unsuccessful.











